Contribute more than a 401(k) allows.A cash balance plan, with a potential tax deduction.
Get my estimateSized by your age and pay, on top of the 401(k) you already have. Our in-house actuarial desk designs it, tests it and files it; you make the decisions. See what your business could contribute in a free PDF.
Free PDF by email. A phone number is required; a call is optional. The PDF estimates contributions. It is not the tax you save.
My Pension Tree, LLC: 401(k) and cash balance plan consultants, with pension actuaries and plan administrators on the team. 25+ years of combined experience. Coral Gables, Florida.
Step 1 of 5 · YOUR BUSINESS
Who works in your business?
Your PDF estimates owner contributions. Employee costs need a separate review.
Owner-only and employer plans are designed differently; this sets which estimate you get and whether a spouse can be included.
An existing plan changes how a cash balance plan is added. MPT reviews it; this estimate stays the same.
Free PDF by email. A phone number is required; a call is optional. The PDF estimates contributions. It is not the tax you save.
My Pension Tree, LLC: 401(k) and cash balance plan consultants, with pension actuaries and plan administrators on the team. 25+ years of combined experience. Coral Gables, Florida.
Choose the plan that fits your business.
Three ways in. Pick the one that sounds like yours.
Business owners with employees
For teams from a handful to fifty-plus. A benefit your team earns by staying, designed and tested on your census.
View employer plansSolopreneur
Just you, or you and a working spouse. A plan your own business funds, sized by your age and pay.
View solo plansPension rescue
Already have an overfunded or frozen plan? Our actuaries review what it can be restructured into.
Get a rescue reviewTraditional pensions are an administrative nightmare.
Disjointed emails, a distant third-party actuary, and a "black box" that leaves the owner, who is legally responsible for the plan, in the dark.
You should understand exactly how your plan works.
A dedicated in-house expert explains the design and the math, gives clear step-by-step guidance, and our platform carries the census, the proposal, the signatures and the annual filings. The owner makes the decisions; the admin headache goes away.
Get my estimateBuilt to hold up.
The three questions owners ask before they sign, answered in plain terms.
- IRS compliance
- Designs prepared by our pension actuaries; the annual calculations, testing and required filings are prepared for you to sign.
- Protection for plan assets
- Assets held in a qualified retirement plan are protected under federal law (ERISA) in ways personal savings are not. Your advisor and CPA confirm how that applies to you.
- Decisions on the record
- Every design comes with the calculations and assumptions behind it, so a question years later has a documented answer.
MyPensionTree vs traditional actuaries and TPAs.
A guided, in-house process instead of the industry's rigid, outsourced one.
Setup and administration
A dedicated in-house expert explains the design while our platform handles the census, the proposal, the signatures and the annual filings. The traditional path is hundreds of dense emails and a "black box".
Plan architecture
Direct, rapid access to the actuaries who design and test your plan, instead of slower communication, rigid rules and finger-pointing between firms.
Who you talk to
The same team runs the plan after it is set up: the annual calculations, the testing and the filings you sign.
An existing plan in trouble
Overfunded or frozen plans are reviewed for what they can be restructured into, and what the actuaries look at first.
Describes how MyPensionTree works and the traditional model it replaces. It is not a claim about any named firm.
Good for the business, not only the owner.
Keep your key people
A vesting schedule rewards the people who stay. Staff earn a contribution over time; owners and key people are weighted by the design.
Flexes with your cash flow
Each year's valuation sets a minimum and a maximum contribution: strong years fund near the top, a weak one can drop toward the minimum. If the business changes durably, the plan can be amended.
Life insurance inside the plan
A qualified plan can hold permanent life insurance on its participants, funded with plan contributions. It is a plan feature, reviewed case by case.
See how it works
In-House Desk
MBA, MS Taxation
The people who run your plan.
"We don't just provide software; we provide hands-on expertise. Every strategy we design is reviewed by our in-house actuarial desk, so the plan is mathematically sound and designed to withstand IRS scrutiny."
Annual actuarial valuation
IRS Sec. 412(e)3 Specialists
Alexander Tecle
President & Founder — MBA, M.S. Taxation
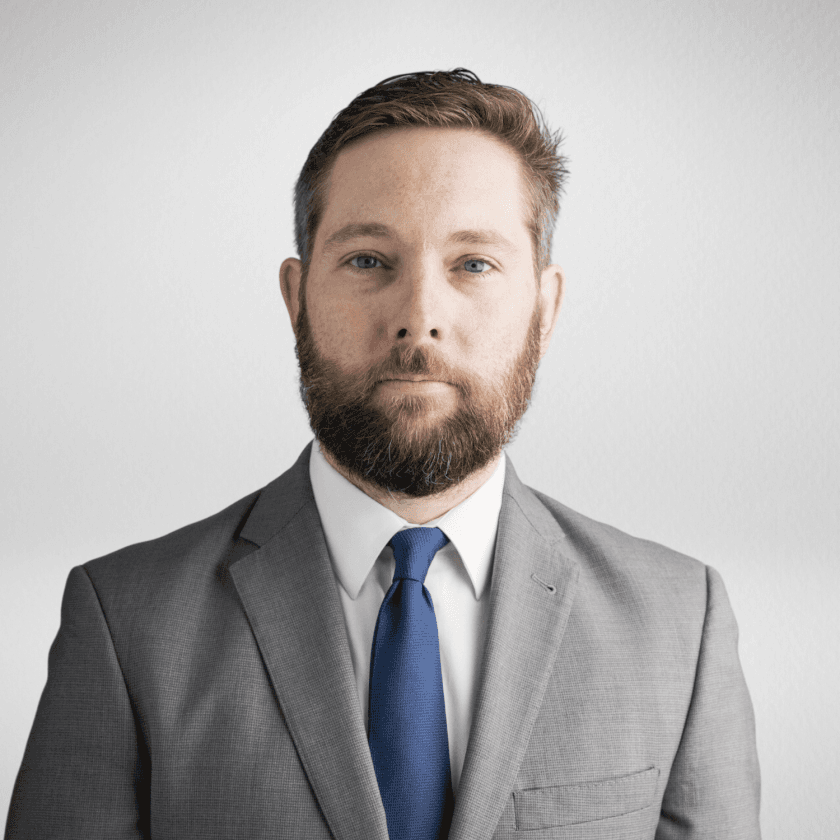
Charles Zimmerer
Wealth Advisor — J.D., CPA · Tax, Accounting & Legal
Three guides owners read first.
Common questions
What is a cash balance plan?
A pension your business funds toward a set retirement benefit, written so that each person has an account balance. The contribution is set by age and pay, which is why older owners can contribute far more than a 401(k) alone allows.
Does it replace my 401(k)?
No. A cash balance plan is added alongside the 401(k) you already have; each has its own limit. An existing SEP or SIMPLE IRA is reviewed first.
What if I have employees?
They are covered by the plan too. The PDF estimates the owner; MPT reviews the employee cost with you after it, before anything is decided.
What does it cost?
The PDF is free. Setup and annual fees are quoted before you start, separately from contributions.
Can I still adopt a plan after the year ends?
Often, yes. Under the SECURE Act a new employer-funded plan can be adopted as late as the extended filing deadline and still count for the prior year. MPT confirms the dates for how your business files; your CPA confirms the deduction.
Who designs and runs the plan?
MPT's in-house pension actuaries and plan administrators design the plan, run the annual calculations and testing, and prepare the filings you sign. Your CPA confirms the tax treatment and your advisor manages the investments.
See what your business could contribute.
Free PDF by email. A call is optional.